Barry Callebaut tempers its recovery
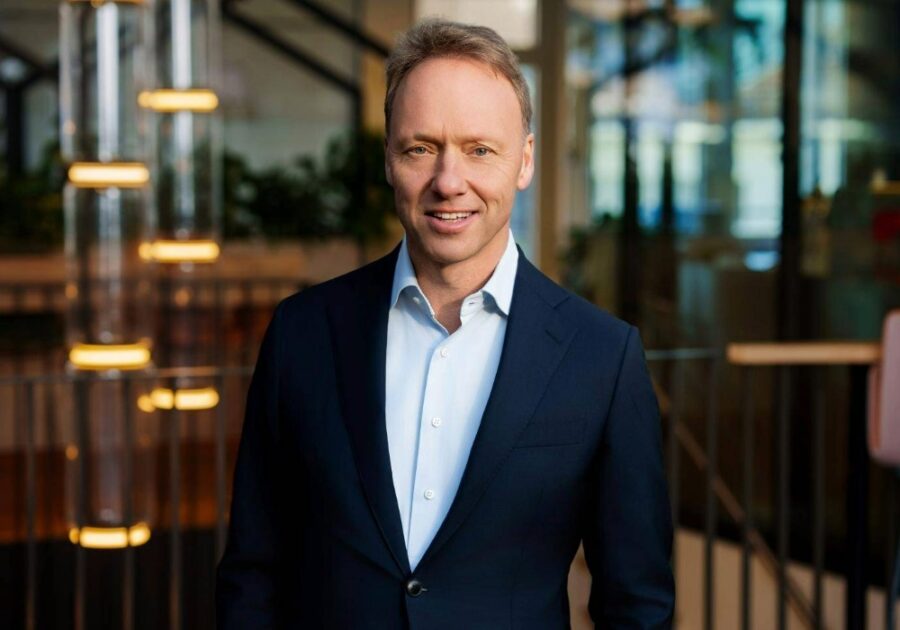
Hein Schumacher, CEO of the Barry Callebaut Group
Barry Callebaut has closed fiscal year 2025/26 with sales down 15.2% to CHF12.2 billion, but a return to volume growth in the second half and a guided 1–3% volume rise for the year ahead point to a business pivoting towards the segments, regions and customers it believes will pay back.
The headline numbers
The fall in sales reflects lower year-on-year cocoa bean-linked sales prices rather than a collapse in demand: group volumes slipped just 0.7% over the year. Recurring operating profit (EBIT) declined 14.1% in constant currencies to CHF604.5 million, a 15.6% decrease in Swiss francs.
The company attributed the performance to the negative impact of temporary Gourmet long positions and lower finance cost pass-through as cocoa bean prices fell.
Gross profit fell 2.9% in constant currencies to CHF1,341.3 million, again partly due to lower finance cost pass-through. Reduced net finance costs helped recover around two-thirds of the absolute decline in recurring EBIT at the recurring profit-before-tax level.
Momentum builds late
The more telling figure for industry is the direction of travel. Barry Callebaut recorded a second consecutive quarter of volume growth in the fourth quarter, with volumes up 5.7%. That outperformed the chocolate confectionery market, which contracted by 4.3% according to Nielsen.
Hein Schumacher, CEO of Barry Callebaut Group, said: “Our FY 2025/26 results demonstrate early progress, including a return to volume growth in the second half of the year, strong free cash flow generation and significant deleveraging.”
Where growth is coming from
Asia Pacific, Middle East and Africa. AMEA was the standout within Global Chocolate, with volumes up 9.8%. Growth was driven by continued momentum in India, market share gains in China and customer wins in Australia.
Gourmet. Volumes rose 0.8% over the year, supported by double-digit growth in the fourth quarter as customers responded to the business’s new pricing cycle.
Cocoa, particularly powder. Global Cocoa volumes declined 1.8% across the year, reflecting weaker market demand in the first half. The second half told a different story, with volumes increasing 12.2%, supported by a lower comparison base and stronger demand following the cocoa market correction, particularly for cocoa powder.
Regional food manufacturers. Within Global Chocolate, which declined 0.5% overall, food manufacturers recorded a 0.7% decrease as challenging market conditions and temporary in-house production shifts among Global Accounts affected performance. Improved momentum among regional food manufacturers partly offset those pressures.
Europe. Central and Eastern Europe recorded 1.1% volume growth, while Western Europe achieved a marginal 0.2% increase, outperforming its declining market.
A narrower focus
The results also show a company being deliberate about where it plays. Schumacher said: “We have also taken decisive action to focus the business on the customers, segments and contracts where we can create the greatest value and build a stronger, more resilient platform for profitable growth.”
For manufacturers who buy from Barry Callebaut, the implication is a supplier that is increasingly selective, with its emphasis on faster-growing segments and profitable, value-added opportunities.
Looking ahead
For fiscal year 2026/27, Barry Callebaut expects volume growth of between 1% and 3%, with performance weighted towards the first half. The outlook reflects its focus on faster-growing segments and profitable, value-added opportunities, despite challenging conditions in Western Europe and North America.
Continuing volume growth
Barry Callebaut’s year was one of lower prices and thinner profit, but the underlying signals are more constructive. Volumes are growing again, it is gaining ground in AMEA while mature markets stay difficult, and cocoa powder demand has rebounded since the cocoa market correction.
The bigger picture is of a supplier outperforming a still-shrinking chocolate market and repositioning around higher-value business. The test in 2026/27 will be whether a first-half-weighted 1–3% volume gain can hold in Western Europe and North America, where conditions remain challenging.